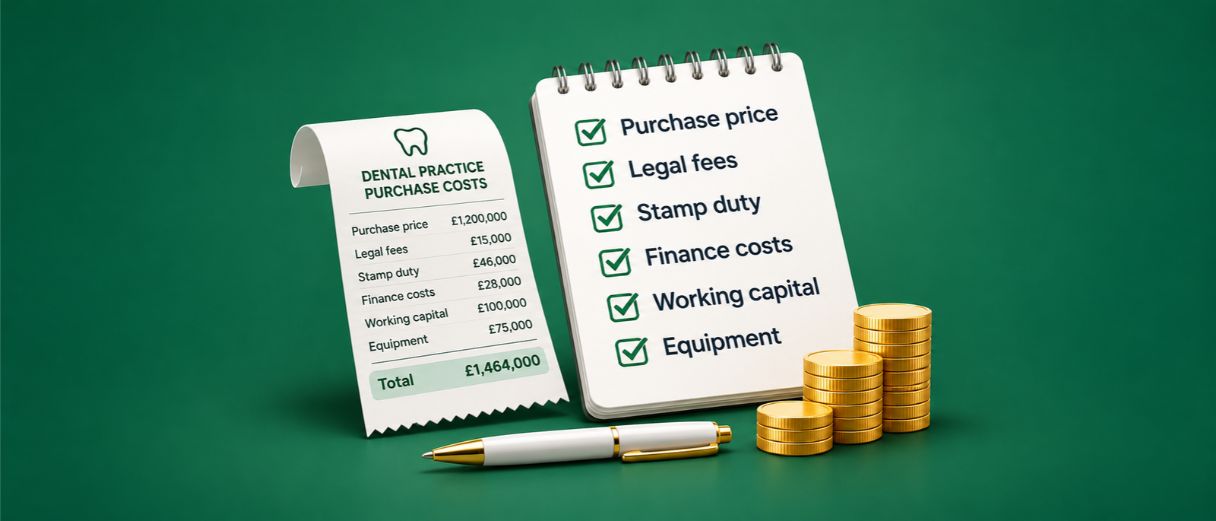
Buying a dental practice costs more than the asking price. Here’s what to budget for, from deposits and professional fees to working capital, and how much a lender may fund.
NJ
By Neha Jain26 min read
Updated November 2026
Ask most buyers what a dental practice costs and they’ll tell you the asking price. Ask a lender, a solicitor or an accountant and you’ll get a longer answer. The price on the brochure is only where the bill starts. Fees, stamp duty, cash in the bank for day one, and the scanner you notice is missing at the first viewing all come on top.
This guide looks at what buying a dental practice really costs, how much of that a lender may fund, and how much has to come out of your own pocket. It sticks to cost and cash.
For the real numbers, Samera spoke to Uros Turcic, Samera’s commercial finance broker. Uros arranges finance for dental practice buyers across the UK, so he sees what a deal actually costs once it reaches the banks, solicitors and valuers. This article draws heavily on that conversation, held in October 2026, including his own words. The figures are a guide and were correct when we wrote this. They change between lenders and between deals.
Reach out find out more about raising finance for your dental practice, whether you’re looking to buy, start or grow your clinic.
The Purchase Price Is Only Part of the Cost
Every practice purchase has two numbers. One is the price you agree with the seller. The other is the total cash you need to find, from the first solicitor’s bill to the day the practice is running smoothly. These two numbers are rarely close, and the gap is where most budgets go wrong.
Here is the whole thing as one formula:
Cash you need = purchase price + acquisition costs + property costs + finance costs + working capital + immediate investment, minus borrowing
Each part has its own section in this article:
Purchase price: the agreed figure for the goodwill, plus the freehold if it’s included.
Acquisition costs: solicitors, financial due diligence and valuations.
Property costs: stamp duty on a freehold, or lease and landlord costs on a leasehold.
Finance costs: arrangement fees, the lender’s legal fees, security documents and any broker fee.
Working capital: the cash you leave in the practice after completion to keep it running.
Immediate investment: the equipment, refurbishment and IT you want to change early on.
Borrowing: whatever the lender agrees to fund, which brings down the cash you need.
A practice can be 90% or even 100% funded and the buyer can still need tens of thousands of pounds in cash. That’s what the formula shows.
There is some good news. You don’t pay everything at once. Completion usually takes around six to nine months for a private practice and nine to twelve months for one with an NHS contract, according to Uros. Many of the costs only fall due late in that time. As Uros puts it:
“You don’t have to pay for everything all in one go. The solicitors and the valuers are towards the beginning, the arrangement fee is only due at completion, and everything else you can save up for as you go.”
Uros Turcic Commercial Finance Broker
How Much Does a Dental Practice Cost?
There’s no single answer, and Uros says so himself:
“It varies. It relies on location, the number of surgeries, whether there’s an NHS contract or it’s fully private, and what services they offer. But what I’m seeing mostly is somewhere in the range of £600,000 to £1.2 million. That’s your day to day situation for an average practice.
I’ve also had cases at £2 million, £1.75 million, or even higher. One of them was a mostly NHS practice with six surgeries. The other was five surgeries with a lot of private work going through it.”
Uros Turcic Commercial Finance Broker
So what moves the price up or down? These are the main things:
Turnover and profit. Buyers and lenders look closely at EBITDA, which is the profit the practice makes before interest, tax and depreciation.
NHS and private mix. The balance changes the pattern of income and how a lender sees the risk.
Location. A busy town with little competition prices differently from a quiet area with several practices close by.
Number of surgeries, and how busy they are. More surgeries can mean more income. They also mean more to run.
Goodwill and the patient base. This is the value of the business itself, not the building.
Equipment. Modern, well looked after kit supports the price. Tired kit means spending money soon after you buy.
Staff and associates. A practice that relies on a few associates carries more risk than one with a settled team.
Whether the freehold is included. This adds the building to the price, and adds a different set of costs.
Two terms come up all the time, and people often mix them up. Uros explains them like this:
“Goodwill is essentially the business side of the practice: the patients, the chairs, the staff, the contracts, everything that makes the business the business. Freehold is just the building the business is in.”
Uros Turcic Commercial Finance Broker
How the deal is set up also changes the cost. You can buy the company’s shares, or you can buy the practice’s assets:
“With a share purchase, you’re buying the shares of the company and inheriting the good, the bad and the ugly: all the contracts, all the complaints, all the good things. With an asset purchase, you pick and choose what you want from the practice.”
Uros Turcic Commercial Finance Broker
A share purchase usually means more checks and more legal work, so the fees go up. An asset purchase is usually cheaper to complete.
How Much Deposit or Equity Does a Buyer Need?
There’s no standard deposit. If someone gives you one figure for every deal, they’re guessing.
As a rough guide to the market now, a first time buyer can sometimes borrow up to about 90% of the goodwill price and up to 100% of a freehold. On a second practice that usually drops to around 80%, and on a third to somewhere between 70% and 80%. Treat these as a guide only. Each case is looked at on its own.
Some lenders will go further and consider funding close to 100% of the business purchase. Uros says it isn’t a simple rule:
“There are certain lenders that will offer 100% LTV. What they base it on is sometimes internal, so I won’t always know. What I do know is how confident they are with the deal, and what the debt service cover says.”
Uros Turcic Commercial Finance Broker
LTV means loan to value. It’s the share of the price the lender will fund. These things all affect it:
Profit. Stronger EBITDA gives a lender more confidence.
Serviceability. Can the practice comfortably pay the loan back and still pay you?
Your experience. Time spent in dentistry counts.
Whether you already work there. Knowing the practice well lowers the risk.
Size and complexity. More surgeries and more associates mean more moving parts.
The valuation. The lender funds against its own valuer’s figure, not the price you agreed.
Existing debt. What you already owe affects what you can take on.
The property. Adding a freehold changes how the deal is set up.
Lender appetite. Lenders want different things at different times.
On knowing the practice and on size, Uros says:
“They’re more comfortable giving you 100% LTV if you already work in the practice and know it well. If a practice has seven or eight associates, it’s a big puzzle, so there’s more risk, and they prefer something smaller.”
Uros Turcic Commercial Finance Broker
On experience:
“There’s more risk when you only have three to five years’ experience, rather than somebody with ten to fifteen years who has seen dentistry for much longer. In the end it’s a puzzle, but it always comes down to serviceability and the debt service cover.”
Uros Turcic Commercial Finance Broker
Serviceability sounds technical, but the idea is simple. A lender takes the practice’s EBITDA, takes away what you’ll draw for yourself, takes away the loan repayments, and looks at what’s left. The exact formula changes from bank to bank, and so does what counts as a comfortable amount. Uros puts it this way:
“It’s how much money will stay in the business after all of your drawings and your loan repayments. If that number is a good number, that’s what they want to see.”
Uros Turcic Commercial Finance Broker
For planning, Uros uses a rough figure of 10% of the deal as the ideal contribution, plus about £25,000 to £30,000 on top for fees. Some lenders ask younger dentists for around 10% because it shows commitment and gives the bank a bit more security.
You also have a real choice to make. A bigger deposit means a smaller loan and less interest over the years. Keeping that cash back means you can spend it on the practice straight away. Which is better depends on what the practice needs from you in its first year.
One thing doesn’t change. Even if a lender funds the full price, it won’t fund your fees, your working capital or your contingency. That money comes from you.
Legal and Professional Fees
Solicitors are one of the two costs buyers most often underestimate. The reason is simple. You usually pay for two sets of legal work, your own and the lender’s.
On your side, Uros gives this range:
“On your side, solicitors vary case by case, from £3,000 to £7,000. An NHS contract, a partnership or a more complex deal can go up to £15,000.”
Uros Turcic Commercial Finance Broker
The lender’s solicitor acts for the bank, and the buyer pays for that too. Uros puts it at a similar £3,000 to £7,000 on average, though he says the exact figure is up to the bank. Share purchases, NHS contracts and partnerships push legal work towards the top of these ranges.
Timing matters as well. Solicitors tend to join once the valuation is back, because there’s no point paying for legal work on a deal that may fall through at the valuation. Some buyers bring them in earlier for peace of mind. That’s fine, but you pay sooner.
The second professional cost is financial due diligence by an accountant. Uros recommends it on every deal and says why:
“I would always suggest a due diligence made by the accountants. It covers a lot more than the seller’s brochure ever would. It goes into the patient book and all of the accounts, and if they pick up on something the brochure won’t show, it can make or break the deal, or change the price quite drastically.”
Uros Turcic Commercial Finance Broker
A full review goes deep into the contracts and accounts and can take four to six weeks. The cost depends on the size and complexity of the practice, so the accountant quotes for it rather than charging a standard rate. If something unexpected turns up, it can reopen the price discussion, which is exactly what you’re paying for.
All of these fees come out of the buyer’s own cash.
Valuation Costs
You can come across three kinds of valuation on the way to completion:
The practice valuation. This is the basis of the price you and the seller agree. The seller’s figures and your own advisers feed into it.
The lender’s valuation. The bank appoints a valuer to check the business is worth what you’ve agreed to pay. This one decides how much the bank will lend.
A freehold or property valuation. If the building is included, it gets valued too.
The lender’s valuation is the one with a direct fee. After the agreement in principle, the bank gives you a panel of valuers to pick from. Uros describes how it works:
“The banks will offer you a panel of valuers to choose from. They range from £2,000 to £4,000 plus VAT. People usually choose whatever fits them well, because some can come to the practice quicker and some take more time.”
Uros Turcic Commercial Finance Broker
Price rarely decides it. Speed and availability usually do.
When the Lender’s Valuation Comes in Low
Every buyer hopes this won’t happen to them. Uros doesn’t play it down:
“It’s one of the worst scenarios that can happen. Say the agreed price was £1 million and the valuers come back and say it’s worth £900,000. There are usually four things that can happen next.”
Uros Turcic Commercial Finance Broker
The four outcomes are:
The seller lowers the price. In this example the seller agrees to £900,000 and you save £100,000. This is the best case.
You meet halfway. You ask the seller to come down by £50,000 and you cover the other £50,000 yourself, making the price £950,000. Some sellers say no.
You pay the gap. The bank only lends against its valuer’s figure, so you pay the whole £100,000 difference from your own cash.
You walk away. If neither side will move, the deal ends.
Walking away still costs money. As Uros says:
“At that point you’ve already incurred expenses such as the valuation itself, and if you involved solicitors before that, you’ll pay for them as well. But maybe saving £100,000 is worth spending seven or ten thousand at that point.”
Uros Turcic Commercial Finance Broker
This is one of the best reasons to keep some cash in reserve, which we cover later in this article.
Finance and Lender Fees
Finance costs are made up of several smaller items. What matters most is which of them can be added to the loan and which you have to pay in cash.
Arrangement fee. This is usually 1% to 2% of the total loan. It looks big, but most lenders let you add it to the loan instead of paying it upfront.
The lender’s legal fees. The buyer pays these. See the legal section above.
Lender valuation fee. Covered in the section above.
Security documents. The paperwork that secures the loan, such as debentures and guarantees that tie companies together.
Broker or adviser fees. These depend on the broker and the type of deal.
On the arrangement fee, Uros says:
“The arrangement fee can look like a higher amount because it’s 1 to 2% of the total loan, but usually lenders will add it on top of the loan itself. It’s only a few lenders that cannot do that.”
Uros Turcic Commercial Finance Broker
The security documents are the cost you see least of, because you don’t know what they’ll be until close to completion:
“These are the security documents and debentures that tie the companies together. They usually come between £200 and £500 per item, and there are usually three to five items. The more complex the deal, the more there are, but on average we’d say about £1,000 to £3,000.”
Uros Turcic Commercial Finance Broker
Buyers sometimes ask about a product fee, the upfront charge that’s common on mortgages. Uros isn’t aware of one being standard, although a small amount may be charged when the loan is drawn. The bank handles that part, so check your offer letter.
Broker fees depend on the deal. Samera doesn’t charge a broker fee when you buy an existing practice with goodwill and freehold. It earns its commission from the lenders. Startup finance is different. There the fee is 2% of the total loan, because there’s more work involved. Other brokers do things their own way, so always ask before you take one on.
Freehold vs Leasehold Costs
Whether the practice is in a leased building or a freehold you’re buying changes the cost list quite a lot. The choice is covered in more depth in our Freehold vs Leasehold article. The cost differences are below.
Leasehold
If you’re taking over a lease, expect:
Legal work on the lease assignment or a new lease
The landlord’s legal fees, which tenants usually have to pay
A licence to assign, where the landlord has to agree
A rent deposit, if the landlord asks for one
Your own solicitor’s time on all of the above
Stamp duty can also apply to a lease, depending on any premium you pay and the rent, so ask your property solicitor early.
Freehold
Buying the building adds a second purchase to the first:
The property price
A commercial mortgage, which is separate from the finance for the goodwill
Stamp Duty Land Tax (SDLT)
A survey and a property valuation
A property solicitor
Land Registry fees
Extra equity, depending on how willing the lender is to fund the property
SDLT is one of the biggest single costs on a freehold purchase, and one of the easiest to forget. For commercial freehold property in England and Northern Ireland, there’s no tax on the first £150,000, 2% on the slice from £150,000 to £250,000, and 5% on anything above £250,000. To see how the bands work, a £275,000 freehold has an SDLT bill of £3,250. On a £750,000 building, the bill is £27,000. Scotland and Wales have their own property taxes with different rates, so check which one applies to you.
“If you’re buying a freehold, there’s always stamp duty to pay, no matter what.”
Structure Matters More With a Freehold
When the freehold is included, the way the funding is set up changes. Usually a second limited company buys the property, and many buyers put a holding company above both companies for capital gains tax and wider tax planning. NHS contracts add another layer, because they’re held by sole traders, not limited companies. Uros’s advice is to sort this out early:
“The only thing that needs to be clear is the structure itself before I approach the bank, so they know how to fund it. That’s a conversation to have with your accountant before the agreement in principle.”
Uros Turcic Commercial Finance Broker
A dental accountant can work out the best structure before any lender is approached.
Working Capital
Working capital is the cash you keep in the practice after completion so it can keep running. It isn’t exciting, and it’s the first thing buyers squeeze when they’re struggling to find a deposit. That’s a mistake.
On day one you own a business with running costs, and the income doesn’t arrive on day one. The practice still has to pay for:
Payroll for nurses, reception and management
Associates, who need paying on time
Lab bills and clinical supplies
Rent and rates
Utilities and insurance
Marketing
Tax, including PAYE and corporation tax, which fall due on fixed dates whatever the cash position
Loan repayments, which start on the lender’s timetable
Income, on the other hand, comes in lumps. NHS payments arrive on a schedule, patient payments come in as treatment is done, and the first few weeks after a change of owner can be uneven. The gap between money going out and money coming in is what working capital covers.
Uros’s answer on how much to keep is short:
“You should save as much as you possibly can. That’s the only answer I can give. You might want to invest in the practice as soon as you start. If there’s no CBCT and you want to do implants or ortho, or the software or hardware is outdated, or you don’t like the reception and want to modernise it, any reason is a good reason, especially if it’s invested back into the practice.”
Uros Turcic Commercial Finance Broker
There’s no standard figure that suits every practice. A practical way to work it out is to add up one month of fixed costs, then decide how many months you want to be able to cover. The less steady the practice’s income, the more months you’ll want.
Can a lender fund any of it? It depends:
“It varies quite a bit, and it’s a conversation you should have with the lender itself.”
Lenders often offer a business overdraft alongside the main loan, which can help with gaps. An overdraft still has to be paid back, so it works best as a backup and not as the plan.
Buying has one clear advantage over starting a practice from scratch. A startup has to wait around two years before taking dividends. A buyer can draw from the first month:
“You can take drawings from the first month. That’s not a problem, because the business is already running and already making profits, so you can foresee how much you can take out.”
Uros Turcic Commercial Finance Broker
None of this changes the main lesson. Don’t put every pound you’ve saved into the deposit.
Post Purchase Investment
Buying the practice and improving the practice are two different costs. It helps to keep them apart in your budget. The first is what you need to complete. The second is what you choose to do afterwards.
Typical examples are:
Imaging: a CBCT scanner, new X ray equipment or intraoral scanners
Surgeries: replacement chairs, delivery units and compressors
Refurbishment: reception, waiting area, decor and flooring
IT and software: new computers, practice management software and cybersecurity
People: recruitment costs for associates, hygienists or nurses
Marketing: a new website, branding and campaigns to bring in patients
How much to set aside depends on the practice you buy, and nobody can tell you from behind a desk. Uros says the budget starts at the viewing:
“That’s something you need to know yourself once you see the practice. That’s why viewings are so important, because only you can see what you need to spend money on and how much it’s going to cost. You’re the first one there. You see, OK, I need a new CBCT, I need new computers, I don’t like the X rays. So you can start preparing at that point. I’m going to need £50,000 or £60,000, and you keep saving it all the way to completion.”
Uros Turcic Commercial Finance Broker
Take a notebook to every viewing and price up anything you’d change. Ask suppliers for quotes. A real number for a CBCT or a full set of chairs is far easier to plan around than a guess.
Some of this spending can be funded separately. Equipment can often be financed through specialist asset finance lenders instead of the main bank, which leaves your cash free for other things. Whether that works for your purchase depends on the lender and the timing, so raise it with your broker early.
There’s no limit on what you could spend. Uros’s view is that money put back into the practice is money well spent. The only rule is not to spend what you need for working capital.
What Can Be Financed and What Usually Needs Cash?
This table shows how each cost is usually treated. It’s a guide only, as lender policies vary and change.
Cost
Usually financed?
Notes
Goodwill (purchase price)
Yes, up to the lender’s LTV
Often up to around 90% on a first purchase. The buyer pays the rest.
Freehold
Yes, usually at a higher LTV
Some lenders fund up to 100% on a first purchase. Lower on later purchases.
Arrangement fee
Usually added to the loan
A few lenders cannot do this.
Your solicitor
No, paid in cash
Usually £3,000 to £7,000, up to £15,000 on complex deals.
Lender’s solicitor
No, paid in cash
Usually £3,000 to £7,000.
Financial due diligence
No, paid in cash
Quoted by the accountant.
Valuation fees
No, paid in cash
£2,000 to £4,000 plus VAT for the lender’s valuer.
Security documents
No, paid in cash
Around £1,000 to £3,000 on average.
Stamp duty (freehold)
No, paid in cash
Payable on the property part of the deal.
Broker fee
Not applicable with Samera
No fee for buying an existing practice.
Working capital
Varies
A lender may offer an overdraft. Keep your own cash too.
Equipment
Often possible separately
Can often be funded through asset finance.
Refurbishment
Usually cash
Ask your lender, as some may consider it.
“All of it has to come from the buyer’s own cash, except the arrangement fee, which can be put on top of the loan. More or less, this is all coming from your pocket.”
Uros Turcic Commercial Finance Broker
Worked Examples
Uros has handled recent deals at around £650,000, £1.75 million and £2 million. These were all goodwill only, and the client details are private. So the three examples below are illustrations. They use the fee ranges Uros gave, taking a sensible point within each range, and the lending levels described earlier. The working capital and investment amounts are planning assumptions, not lender rules. Your own figures will be different.
Example A: A £500,000 Leasehold Practice
Item
Amount
Purchase price (goodwill)
£500,000
Bank lending (90%)
£450,000
Buyer contribution (10%)
£50,000
Your solicitor
£4,000
Lender’s solicitor
£4,000
Lender valuation (£3,000 plus VAT)
£3,600
Security documents
£1,000
Arrangement fee (1.5% of loan, added to the loan)
£0 cash
Cash needed by completion
£62,600
Working capital (assumption)
£30,000
Immediate investment (assumption)
£20,000
Total cash required
£112,600
Example B: A £1 Million Leasehold Practice
Item
Amount
Purchase price (goodwill)
£1,000,000
Bank lending (90%)
£900,000
Buyer contribution (10%)
£100,000
Your solicitor
£6,000
Lender’s solicitor
£6,000
Lender valuation (£3,500 plus VAT)
£4,200
Security documents
£2,000
Arrangement fee (1.5% of loan, added to the loan)
£0 cash
Cash needed by completion
£118,200
Working capital (assumption)
£50,000
Immediate investment (assumption)
£50,000
Total cash required
£218,200
Example C: A Practice Plus Freehold
Item
Amount
Goodwill price
£1,000,000
Freehold price
£750,000
Total price
£1,750,000
Bank lending on goodwill (90%)
£900,000
Bank lending on freehold (100%, first purchase)
£750,000
Total bank lending
£1,650,000
Buyer contribution on goodwill
£100,000
Your solicitor
£10,000
Lender’s solicitor
£8,000
Lender valuation (£4,000 plus VAT)
£4,800
Security documents
£3,000
Stamp duty on the freehold
£27,000
Arrangement fee (1.5% of loan, added to the loan)
£0 cash
Cash needed by completion
£152,800
Working capital (assumption)
£60,000
Immediate investment (assumption)
£50,000
Total cash required
£262,800
A few costs vary too much to give a fair figure. The totals above leave out financial due diligence in all three examples, landlord and lease costs in the two leasehold examples, and the survey and Land Registry fees in the freehold example. Add your own quotes for those.
A few things stand out:
Even with 90% borrowing, the total cash needed comes to around 15% to 23% of the purchase price once fees, working capital and investment are added.
The deposit is often less than half of the real cash requirement. In Example A, the £50,000 deposit is under half of the £112,600 total.
Stamp duty on a freehold can be the biggest single fee. In Example C it’s £27,000.
A high LTV on the freehold keeps the deposit down, but it doesn’t remove the fees, the tax or the need for working capital.
Why the Cheapest Practice Is Not Always the Easiest to Finance
A lower price looks tempting. Lenders care less about the headline price than about cash flow and serviceability. In other words, does the practice make enough profit to pay the loan, pay you, and still have something left over?
A cheaper practice can be harder to finance when:
Profit is weak. If the loan is close to the practice’s EBITDA, there’s no room to manoeuvre. Uros is blunt about it: “If I see your loan is pretty much the same amount as your EBITDA, and you still have to make money from it, it’s a no go.”
Income is falling. Lenders look at which way the numbers are heading, not just the latest year.
The lease is poor. A short or restrictive lease can worry both the buyer and the lender.
The records are weak. Gaps or mismatches in the accounts slow everything down.
Big spending is needed. If the practice needs major equipment straight away, that cash has to come from somewhere.
Uros describes what an easy practice looks like:
“If the EBITDA makes sense, your drawings are relatively low and the debt service cover is above 1.5 times, that tells me it’s going to be a very easy practice to finance. Why? Because there’s very little to go wrong. If you keep everything going the way it was and replace the current principal owner effectively, there’s very little chance anything goes wrong.”
Uros Turcic Commercial Finance Broker
That usually means smaller practices, often two, three or four surgeries. It gets harder as the number of associates, the number of surgeries and the price go up.
The match between buyer and seller counts too. If the seller is an implantologist and the buyer doesn’t do implants, lenders will still fund it, but the profit forecast changes:
“If the current principal is an implantologist and you don’t do implants, they will still finance, but the EBITDA is going to go down, because you have to straight away hire another associate to cover the implants.”
Uros Turcic Commercial Finance Broker
The reverse is what lenders like to see:
“Your best case scenario is somebody who’s retiring and does the core services, like ortho and restorative, while you do implants, perio, everything above and beyond. You can take over their services and straight away increase profit and EBITDA, and that’s what the banks love to see: somebody who can bring in and make more money.”
Uros Turcic Commercial Finance Broker
Chair occupancy is the quiet factor many buyers miss:
“Chair occupancy is quite important, which a lot of people don’t mention. If it’s at 90 or 100%, there’s very little space to grow, because you’d need a new surgery and there’s no room. But if it’s at 60 or 70%, there’s another 30% of chair time you can fill, so you can start offering services that weren’t there before and put more patients on the chairs.”
Uros Turcic Commercial Finance Broker
So a cheap practice that’s already full and barely profitable can be harder to fund than a dearer one with spare capacity and strong earnings. The price tag tells you very little. The numbers underneath tell you a lot.
How Much Cash Should You Have Before You Start Looking?
The best time to do this sum is before you make an offer, not after. An easy way is to build your own version of the formula:
Your available savings. What you can realistically put in without leaving yourself short.
Your likely equity contribution. Use around 10% of the price for planning, then adjust once a lender gives you real terms.
Fees. Solicitors, the lender’s legal costs, valuation, security documents and due diligence. Uros’s rough planning figure for fees is £25,000 to £30,000 on a typical deal.
Stamp duty, if a freehold is included.
Working capital. Several months of fixed costs is a sensible place to start.
Contingency. A cushion for surprises, including a valuation that comes in low.
Investment after completion. The equipment and refurbishment you spotted at the viewings.
Add these up and compare the total with your savings. If you’re short, you have time to close the gap. Completion is often six to nine months away on a private practice and longer on an NHS one, so you can keep saving right up to completion day.
The mistake Uros sees most often is skipping this step and guessing:
“The biggest mistake is not getting professional advice when doing the calculations. I have conversations with people who think they need a 30% deposit, or no deposit at all, or who heard from a friend of a friend’s accountant that they don’t need to pay stamp duty. Talk to professionals, find out what the real fees are, and start saving as much as you can.”
Uros Turcic Commercial Finance Broker
How Samera Can Help
Working out the true cost of a practice is much easier with someone who sees these deals every week. Samera’s commercial finance team can help you build a realistic cash budget before you make an offer, approach a wide range of lenders for you, and stay involved through valuation, due diligence and completion. Samera’s accountants can also advise on the right structure, especially where a freehold or an NHS contract is involved.
Whether you’re only starting to look at practices or already have one in mind, the Samera team can help you work out what you’ll really need and what the sensible next step is.
Need help buying a practice?
Samera has helped dentists buy, start and sell practices since 2002, and we own dental practices ourselves. If you’d like support finding, financing or completing a purchase, book a free call with our team, or reach out and we’ll get back as soon as we can.
Neha Jain is a skilled content writer with a rich background in business and financial knowledge. With a bachelor’s degree in English Literature and Psychology, Neha has honed her writing skills, furthering her expertise with the Content Writing Master Course (CWMC) at IIM SKILLS and a Content Marketing Certification from HubSpot Academy.
Working alongside our business development experts, Neha specialises in helping accountants, dentists and other healthcare professionals start, scale and sell their businesses.
Uros Turcic is Samera’s in-house commercial finance broker. He arranges acquisition, startup and asset finance for dentists across the UK, working directly with lenders to secure the right terms. He supports clients through every stage of the application, from preparing documents and financial projections to agreement in principle and completion
1000+
Practices supported
Live · 4 specialists available
Book a free virtual consultation with one of our specialists and discover what Samera can do for your practice.
By booking you agree to our privacy policy. We’ll never share your details.
We use cookies
We use cookies to make the site work, and, only if you say it's OK, to measure
how it's used and improve it. You can change your mind any time from the
Cookie Policy.
Essential
Required for the site to work — page navigation, booking modal, contact forms, basic preferences. Always on.